.svg)
For businesses that accept card payments, customer disputes are an unavoidable part of commerce. A customer may be unhappy with a purchase, fail to recognize a transaction, receive a damaged product, or believe they were charged incorrectly. When that happens, two terms often enter the conversation: refunds and chargebacks.
Although both can result in money being returned to a customer, they are fundamentally different processes.
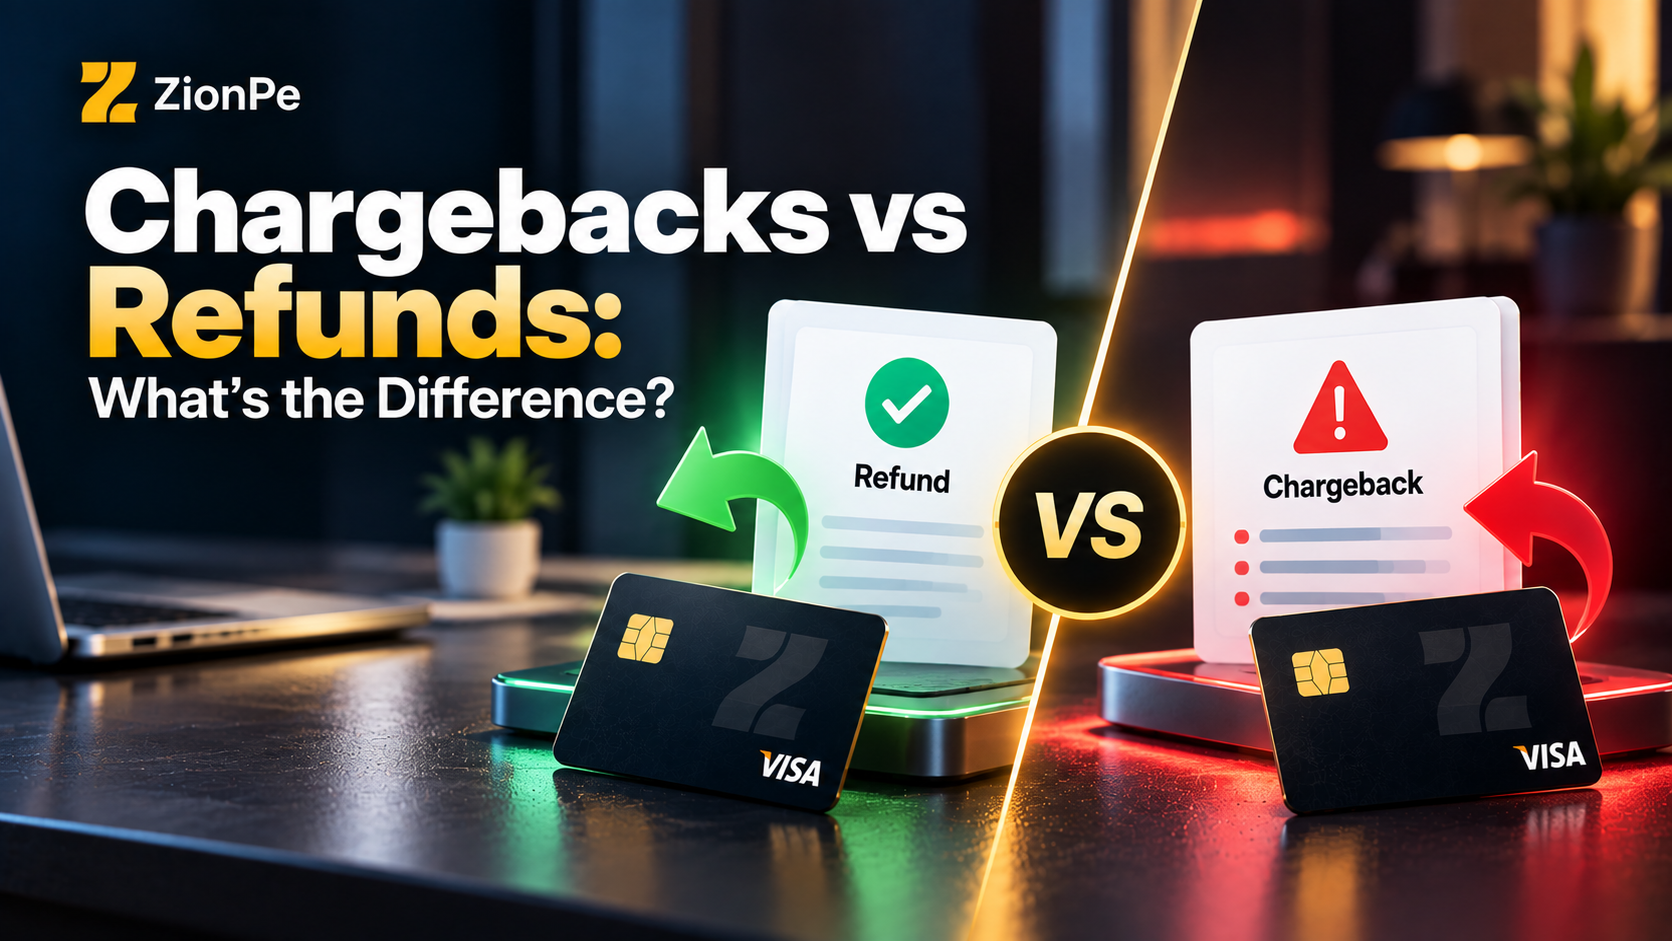
A refund is generally initiated by the merchant, while a chargeback is initiated by the customer through their card issuer. The difference matters because chargebacks can involve additional fees, administrative work, evidence requirements, and potential consequences for a merchant’s payment operations.
Understanding how each process works can help businesses resolve customer issues efficiently, reduce unnecessary disputes, and build a more effective payment-management strategy.
What Is a Refund?
A refund occurs when a merchant voluntarily returns some or all of a customer's payment.
For example, imagine a customer purchases a $200 product online but later discovers that it does not meet their needs. They contact the merchant, and the business agrees to return the full $200 to the customer's original payment method.
That is a refund.
Refunds can be issued for a variety of reasons, including:
- Product returns
- Cancellations
- Duplicate payments
- Incorrect charges
- Damaged or defective products
- Failed or delayed services
- Customer satisfaction issues
- Merchant-approved exceptions
The important point is that the merchant controls the refund decision.
In most cases, the merchant processes the refund through its payment processor or payment gateway, and the funds are subsequently returned to the customer's payment method.
What Is a Chargeback?
A chargeback is a formal payment dispute initiated by a cardholder through their bank or card issuer.
Instead of contacting the merchant and asking for their money back, the customer contacts the financial institution that issued their card and disputes the transaction.
The issuer then reviews the dispute and, depending on the circumstances, may initiate the chargeback process.
Common reasons for chargebacks include:
- The customer does not recognize the transaction
- The customer claims they did not authorize the payment
- The product or service was not received
- The product was significantly different from its description
- The customer was charged multiple times
- The merchant did not provide an agreed refund
- The customer believes the transaction was processed incorrectly
Once a chargeback is initiated, the merchant may have an opportunity to provide evidence showing that the transaction was legitimate or that the merchant fulfilled its obligations.
This makes a chargeback fundamentally different from a normal refund: the dispute is handled through the card-payment dispute process rather than being resolved directly between the merchant and customer.
Chargebacks vs. Refunds: The Key Difference
Refund: Initiated by the merchant and used to return money to a customer after a return, cancellation, error, or approved request.
Chargeback: Initiated by the customer through their bank or card issuer when they formally dispute a transaction.
Refund = Merchant-initiated | Chargeback = Customer-initiated
Refund: Usually handled directly between the merchant and payment processor.
Chargeback: Involves the customer’s card issuer and the formal payment dispute process.
Refund: Generally gives the merchant more control over the resolution.
Chargeback: May require the merchant to provide evidence supporting the transaction.
Refund: Usually has a straightforward resolution process.
Chargeback: Can involve additional fees, administrative work, and dispute deadlines.
How Does the Refund Process Work?
Although exact procedures vary between payment providers, the general refund process looks like this:
1. Customer requests a refund
The customer contacts the business and explains why they want their money back.
2. Merchant reviews the request
The merchant checks its refund policy, order information, delivery records, and other relevant details.
3. Merchant approves the refund
If the request meets the business's terms, the merchant authorizes the refund.
4. Payment processor processes the transaction
The refund is submitted through the merchant's payment infrastructure.
5. Customer receives the funds
The money is returned to the original payment method, subject to the processing timelines of the relevant payment providers and financial institutions.
For businesses, refunds can therefore be a relatively controlled way to resolve customer dissatisfaction.
How Does the Chargeback Process Work?
Chargebacks involve more parties and can be considerably more complex.
1. Customer disputes the transaction
The cardholder contacts their bank or card issuer.
2. Issuer reviews the dispute
The issuer determines whether the dispute meets the relevant requirements for investigation.
3. Chargeback is initiated
If applicable, the disputed transaction is reversed or otherwise placed into the dispute process, and the merchant is notified through its payment provider.
4. Merchant reviews the claim
The merchant can determine whether the dispute appears legitimate or whether it should challenge the chargeback.
5. Merchant submits evidence
If the merchant contests the dispute, it may provide documentation such as:
- Order confirmations
- Receipts
- Shipping records
- Delivery confirmation
- Customer communications
- Refund policies
- Terms and conditions
- Authentication information
- Product or service records
6. Issuer and relevant payment parties evaluate the case
The dispute is assessed under the applicable card-network and issuer rules.
7. The outcome is determined
Depending on the evidence and applicable rules, the chargeback may be upheld or reversed.
Because chargeback procedures vary according to payment method, card network, geography, and dispute reason, merchants should follow the specific requirements provided by their payment processor.
Why Do Customers Request Refunds Instead of Chargebacks?
From a customer perspective, contacting the merchant first is often the simplest way to resolve a problem.
Suppose a customer accidentally purchases the wrong product. If the merchant has a clear return policy and promptly issues a refund, there may be no reason for the customer to contact their bank.
This is beneficial to both parties.
The customer receives a resolution, while the merchant avoids unnecessary dispute-management costs and administrative work.
Businesses should therefore make their refund policies easy to find and provide customers with accessible support channels.
Why Do Customers File Chargebacks?
Customers may turn to their card issuer when they believe a transaction is fraudulent, when they cannot resolve an issue with the merchant, or when they believe the merchant has not provided the goods or services promised.
One particularly important category is unrecognized transactions.
A customer might see a transaction on their statement that they do not recognize. That does not necessarily mean the transaction is fraudulent the merchant name appearing on the statement may differ from the brand name customers remember.
Clear billing descriptors, transaction receipts, and accessible customer support can help reduce this type of confusion.
Other disputes can arise from genuine disagreements about delivery, product quality, cancellation policies, recurring billing, or authorization.
Chargebacks Can Be More Expensive Than Refunds
A refund and a chargeback both potentially return money to a customer, but the cost structure can be different.
With a refund, the merchant generally knows that it is returning the transaction amount and can manage the decision internally.
A chargeback may involve additional consequences, such as:
- Chargeback-related fees
- Lost merchandise or services
- Administrative costs
- Time spent collecting evidence
- Payment-processing complications
- Potential effects on the merchant's dispute metrics
The precise financial impact depends on the merchant's payment provider, business model, transaction volume, geography, and applicable card-network rules.
For this reason, businesses should not view refunds and chargebacks as interchangeable.
Refunds Can Help Prevent Some Chargebacks
A responsive refund process can be an important part of chargeback prevention.
Consider this example:
A customer receives an incorrect item and contacts the merchant. The business responds quickly, accepts responsibility, and processes a refund.
The customer has little reason to escalate the matter to their card issuer.
Now consider the opposite scenario. The customer cannot reach the merchant, the refund policy is difficult to understand, and support requests go unanswered.
The customer may decide that contacting their bank is the next available option.
This is why customer service and payment-dispute management are closely connected.
How Businesses Can Reduce Chargebacks
There is no way to eliminate every chargeback, particularly when fraud and unauthorized transactions are involved. However, businesses can take practical steps to reduce avoidable disputes.
1. Make billing descriptors recognizable
Customers should be able to identify your business from their card statement.
An unfamiliar billing descriptor can lead to legitimate transactions being reported as unrecognized.
2. Provide clear receipts
Send customers confirmations that clearly explain:
- What they purchased
- How much they paid
- When the payment was processed
- The merchant or brand name
- How to contact customer support
3. Publish a clear refund policy
Customers should understand your rules before they purchase.
Explain return windows, eligibility requirements, cancellation procedures, and refund timelines in straightforward language.
4. Maintain delivery records
For ecommerce businesses, documentation can be particularly valuable.
Keep appropriate records of:
- Order details
- Shipment tracking
- Delivery confirmation
- Customer communications
- Product information
These records may become useful if a transaction is later disputed.
5. Monitor recurring payments
Subscription businesses should make cancellation procedures clear and avoid confusing billing practices.
Customers who believe they have canceled a subscription but continue to see charges may dispute the transactions.
6. Respond quickly to customer complaints
A fast response can sometimes resolve an issue before it becomes a formal payment dispute.
7. Use appropriate fraud-prevention measures
Businesses should evaluate available payment authentication and fraud-management tools appropriate to their market and risk profile.
However, fraud prevention should be balanced with the customer experience. Excessive friction can also affect legitimate transactions.
What Happens If a Merchant Loses a Chargeback?
If the chargeback is upheld against the merchant, the disputed amount generally remains reversed, subject to the applicable payment rules and process.
The merchant may also face associated fees or other costs depending on its payment provider.
The precise outcome depends on the dispute type and applicable rules.
This is why documentation matters.
A merchant that receives a dispute should carefully review the reason code or dispute category and submit only relevant, accurate evidence within the required timeframe.
Can a Customer Get Both a Refund and a Chargeback?
This is an important area for merchants to monitor.
Suppose a business has already refunded a transaction, but the customer also files a chargeback for the same purchase.
That can create a duplicate-resolution problem.
Businesses should maintain accurate records of refunds and transaction adjustments so they can identify situations where a disputed payment has already been refunded.
Again, the exact handling depends on the payment provider and dispute process, but good transaction records are essential.
Chargebacks vs. Refunds for Ecommerce Businesses
For ecommerce companies, the distinction becomes particularly important because the customer, merchant, payment processor, shipping company, and card issuer may all be involved in resolving a transaction issue.
A robust ecommerce payment strategy should therefore cover both:
Refund management:
How quickly and consistently the business handles legitimate customer requests.
Chargeback management:
How the business detects, responds to, and learns from payment disputes.
The two processes should not be managed in isolation.
For example:
if a business notices repeated chargebacks associated with customers claiming that orders were never delivered, that pattern could indicate a fulfillment, shipping, fraud, or customer-communication problem.
Chargeback data can therefore provide useful operational insight not just a financial headache.
Chargeback Prevention Is More Than Fraud Prevention
One common misconception is that chargebacks are exclusively a fraud problem.
Fraud is certainly an important source of disputes, but chargebacks can also result from operational and customer-experience issues.
A business may experience disputes because:
- Customers misunderstand its billing model
- Cancellation processes are unclear
- Product descriptions are inaccurate
- Delivery expectations are poorly communicated
- Customer support is difficult to reach
- Refunds take too long
- Subscription billing is confusing
- The business uses an unfamiliar statement descriptor
In other words, reducing chargebacks requires more than detecting fraudulent transactions.
It can require improvements across payments, customer service, fulfillment, billing, and communication.
Frequently Asked Questions
Is a chargeback the same as a refund?
No. A refund is generally initiated by the merchant, while a chargeback is initiated by the customer through their card issuer as a formal transaction dispute.
Which is better for a merchant: a refund or a chargeback?
They serve different purposes. A refund is a direct merchant-controlled resolution, while a chargeback is part of a formal card dispute process. The appropriate response depends on the circumstances of the transaction and the merchant's policies.
Can a merchant refuse a refund?
Whether a merchant can refuse a refund depends on the applicable law, contract, advertised refund policy, payment rules, and circumstances of the transaction. Businesses should ensure their policies comply with the laws and regulations applicable to their customers and operations.
Do refunds affect chargeback rates?
A refund itself is not the same thing as a chargeback. However, an effective refund and customer-service process may help resolve some customer complaints before they escalate into formal disputes.
Can a chargeback be reversed?
Potentially. If a merchant successfully challenges a dispute with appropriate evidence, the outcome can be reversed depending on the applicable dispute process and rules.
How long does a refund take?
The timing varies according to the merchant's payment provider, payment method, card issuer, and other factors. Businesses should communicate realistic timelines rather than promising an exact settlement date they cannot control.
Final Thoughts
The difference between a chargeback and a refund comes down to who initiates the process and how the dispute is handled.
A refund is typically a direct transaction between the merchant and customer. A chargeback involves the customer's financial institution and the formal payment-dispute system.
For businesses, understanding this distinction is more than a terminology exercise. A well-designed refund process, transparent billing practices, responsive customer support, accurate transaction records, and appropriate fraud controls can all contribute to better payment operations.
The goal should not simply be to avoid every refund or dispute. Instead, businesses should focus on resolving legitimate customer issues efficiently while identifying and preventing avoidable payment disputes.
As digital commerce continues to expand, effective payment and dispute management can become an important part of protecting revenue, improving customer trust, and maintaining a healthy merchant operation.